 ▶
Monte Carlo estimator
Independent and identically distributed samples contribute equally to the empirical average.
Approximating unknown quantities from sample averages
If a random variable has expectation r, the average of independent copies converges to r. This turns probability into a general numerical method.
The essential idea: rewrite the desired quantity as an expectation, sample repeatedly, and average.
Independent and identically distributed samples contribute equally to the empirical average.
The standard error shrinks slowly: ten times less uncertainty usually costs one hundred times more samples.
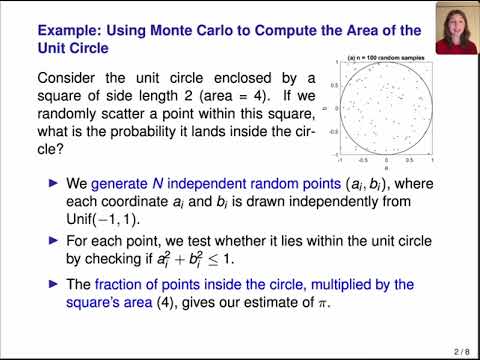
Scatter points uniformly in a square. The fraction landing inside the unit circle estimates its area and therefore π.
Blue points fall inside the circle; pale red points fall outside. At large N, a representative subset remains visible while the estimate uses all samples.
Monte Carlo converts deterministic quantities into expectations, then approximates them with random numerical samples.